
Every major market boom has been driven by a handful of companies that for a while, successfully captured the imagination of investors. Railroad stocks accounted for about 63% of the US market in the 1880s. Japanese companies made up 44% of the MSCI World Index at the peak of Japan's asset bubble in 1989, while technology and telecom stocks reached 41% of the S&P 500 during the dot-com boom in 2000.
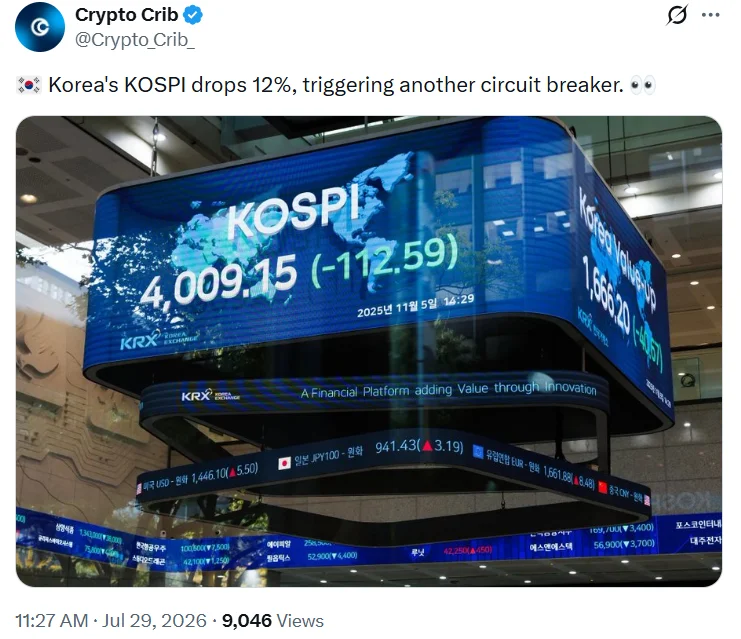
It's now South Korea's turn in the sun (or bubble). By mid-June, its benchmark index KOSPI had nearly doubled for the year, led by memory chipmakers Samsung Electronics and SK Hynix. They accounted for over half of KOSPI’s market capitalization and more than 70% of the gains.
But over the past month, KOSPI has taken a tumble as investors question the massive AI spending.
The same questions are seeping into the US. As investors turn into worrywarts, Tesla lost more than 12% after its latest earnings. IBM erased about a quarter of its market value in a single day. Netflix also saw a sharp post-earnings drop despite adding subscribers and raising its outlook.
The AI spending spree is unprecedented. Hyperscalers are expected to spend nearly $700 billion on AI infrastructure this year, with Microsoft and Oracle alone accounting for over $230 billion. And the growth guidance for these businesses is heavily dependent on a few companies. OpenAI for example, makes up roughly 45% of Microsoft's commercial backlog, and more than half of Oracle's backlog through the Stargate project.
With open-source Chinese models rivalling American ones in capabilities, investors are looking for stronger guidance, and clearer evidence that the billions of dollars being spent on AI will eventually produce bigger profits.
AI rally drives S&P 500 concentration risk higher
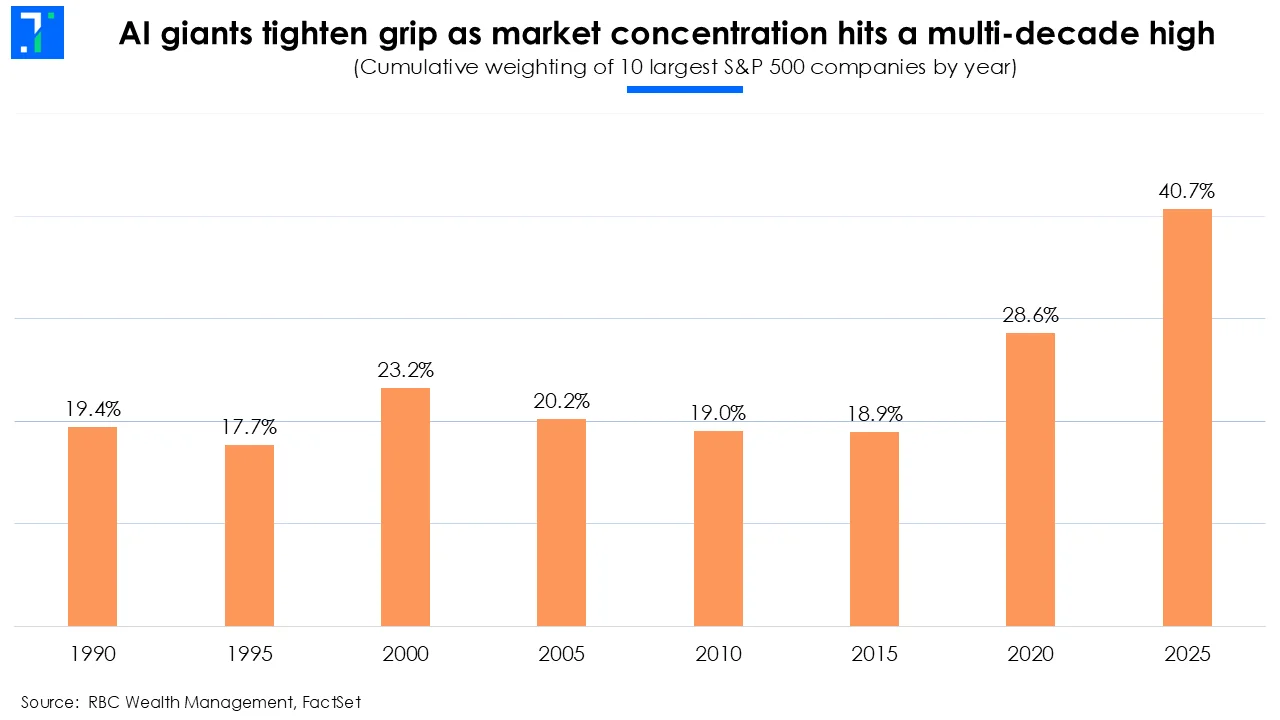
Bank of America says today's AI Big 10 make up roughly 40% of the S&P 500. The group includes Nvidia, Microsoft, Alphabet, Amazon, Meta, Apple, Tesla, Broadcom, AMD and Micron.
The Nasdaq Composite surged 21.4% during Q2 2026, its strongest quarterly gain since the post-pandemic rally of 2020. Chipmakers, memory suppliers and companies building AI infrastructure accounted for much of that advance. Even Elon Musk's SpaceX IPO added to the excitement around technology stocks.
However, as earnings season started in July, the index has plunged more than 10% over the past month, entering correction territory. The volatility these stocks are seeing are more suited to microcaps than index bigwigs.
Alphabet's Q2 earnings showed how high expectations have become. Revenue continued to grow, but investors were more focused on its plan to spend up to $205 billion on AI infrastructure this year. Russ Mould, investment director at AJ Bell, said, “Alphabet is spending hundreds of billions of dollars to stay ahead in the AI race. But investors are still unsure whether those investments will generate enough returns.”
Chinese AI companies such as Moonshot AI and DeepSeek are hitting growth plans for American AI businesses, by making advanced AI much cheaper to run. Moonshot AI's Kimi K3 charges $15 per million output tokens, compared with $50 for Anthropic's Claude Fable 5. Microsoft has reportedly started testing the Kimi model for some workloads as it looks to reduce inference costs by up to 70%.
Tesla more than doubled its capital spending to $5.8 billion as it invested heavily in AI, robotaxis and humanoid robots. The spending pushed free cash flow to negative $1.1 billion for the first time in more than two years, while automotive gross margin also missed expectations. Tesla is facing stiff competition from Chinese rivals, with BYD selling more battery electric vehicles than Tesla last year. Xiaomi, XPeng and other Chinese automakers are launching newer models at lower prices.
Superstar investors see US stock market in bubble territory
The S&P 500's forward price-to-earnings (PE) ratio stood at 22.2, according to LSEG Datastream. That's more than 40% above its 40-year average of 15.8.
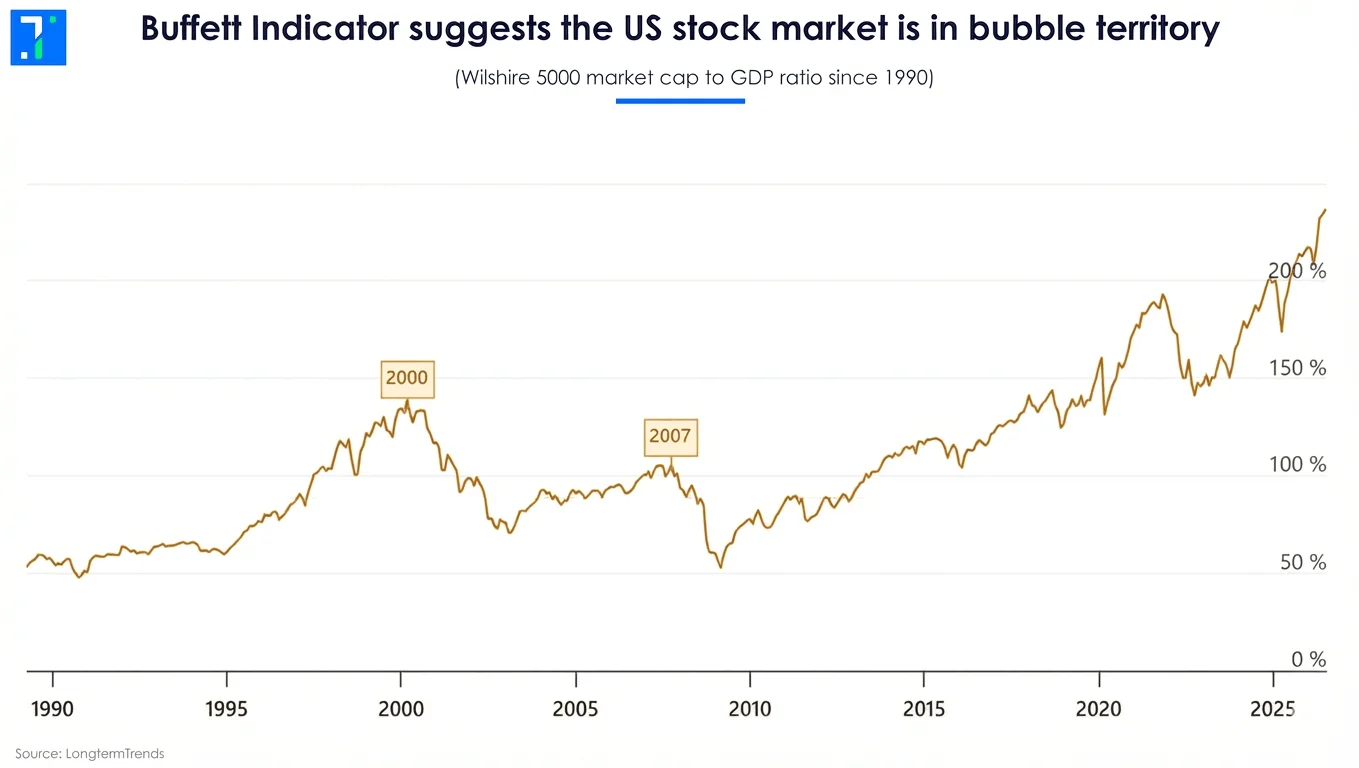
The Buffett Indicator has climbed to around 236%, well above the 200% level that Warren Buffett once described as investors “playing with fire.” The ratio crossed 190% in late 2021 before the market entered a bear market the following year.
Berkshire Hathaway ended Q1 2026 with a record $397.4 billion in cash and Treasury bills, the largest cash reserve in the company's history. Even so, Buffett and Greg Abel have continued adding to Berkshire's Alphabet stake, with Buffett believing the stock could outperform 90-95% of Wall Street's picks.
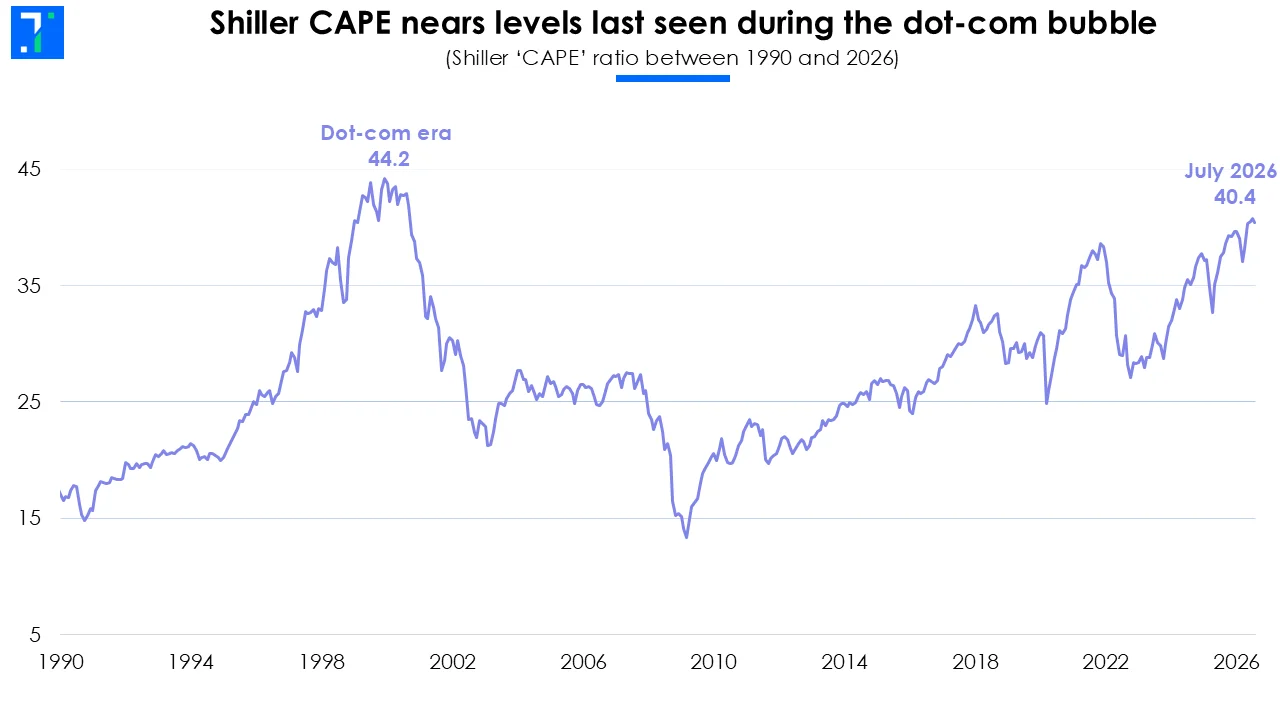
The Shiller CAPE ratio, which measures valuations using average earnings over the past 10 years, has climbed above 40. The last time it reached those levels was during the dot-com bubble, when it eventually peaked at 44.2.
Jeremy Grantham, known for calling the dot-com bust and the 2008 financial crisis, pointed out a trend where leaders of the previous bull market start to underperform while the overall market continues to rise. He believes the US market has entered a “superbubble” and warns stocks could fall by as much as 70%, although he has made similar warnings well before previous market corrections.
“By pretty much every historical metric, the market's valuation is rich,” said Keith Lerner, co-chief investment officer at Truist Advisory Services. The question investors are grappling with is whether those valuations are justified.